Have Uncleared Margin Rules Impacted Swap Activity?

We’re all aware that in the US, the new Uncleared Margin Rules (UMR) took effect on September 1st. Except they kinda didn’t take effect. There was this chestnut of No-Action relief issued by the CFTC on the day, which, if you just read the headline news reports, meant that the Rules were pushed back 1 […]
Defering Bilateral Margin Rules with Low Hanging Fruit

For all those Category 1 Covered Entities in the US and Japan, the following few days should be interesting with the introduction of Bilateral Margin Rules. For all entities not yet covered by the rules, you have some time on your hands. And this time should be used wisely. As a brief reminder, all covered […]
Cross Currency Swaps – how much margin will they need?
We look at the Standardised Schedule of Initial Margin for non-centrally cleared derivatives Cross Currency Swaps are a large part of the uncleared market that we did not look at last week We therefore take a look at the July volumes to estimate Initial Margin requirements for cross currency swaps Margin Requirements for non-centrally cleared derivatives The […]
How much Initial Margin will Uncleared Derivatives require in the first month of trading?

Uncleared Margin Rules (UMR) come into effect as of 1st September So let’s play a fun little game. Take the SDR data for Uncleared Derivatives. Import this data into CHARM, our Initial Margin and Risk tool. Make a few broad assumptions about the trades and the Dealer market. We end up with an estimate of how much IM […]
Higher Swap Margins after Brexit
Last week I looked at Brexit – The Impact on Swap Margin and stated that we will start to see increases in Initial Margin particularly for GBP Swaps. Now that a week has passed lets look at the what the data shows. Cleared IRS 10Y Lets start by using CHARM to calculate the IM of 10Y par vanilla swaps […]
BREXIT – The Impact on Swap Margin
Given the large moves in Swap rates that we highlighted in our BREXIT Day One and Day Two blogs, I thought it would be interesting to look at the impact on Swap margins. Cleared IRS 10Y Lets start by using CHARM to calculate the IM of 10Y par vanilla swaps in EUR, GBP and USD. Showing that on 23 […]
Margin Valuation Adjustment
While it all began many years ago with Credit Valuation Adjustment (CVA), a number of new XVAs have risen to prominence in the last few years such as DVA, FVA, MVA, KVA. Chris wrote about Funding Valuation Adjustment (FVA) last week, so today I will look at Margin Valuation Adjustment (MVA). Background MVA arises when Initial […]
FVA for Cleared Swaps
We’ve recently added Margin Valuation Adjustment analysis into CHARM. As we’ve talked about in the past (here and here), MVA is a cost to the business because Initial Margin has to be funded for the holding period of a trade. This blog considers FVA – Funding Valuation Adjustment – caused by the Variation Margin of trades. All Swaps impart a […]
Compression in Swaps
We run a real compression exercise through CHARM… …showing the potential IM reduction from a compression run Depending on the exact portfolio, the ratio of NPV unlocked to the IM released can be highly variable…. …taking a recursive process to accurately assess your capital efficiency. This is exactly why pre-trade analysis of Compression using high quality, high performance engines such […]
AUD swap market: Concentration risks from the Clearing Mandate
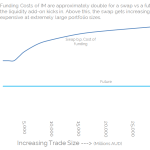
We present a uniquely Clarus view of the AUD IRS markets Our analysis of the regulatory landscape, bond issuance data and swap market flows suggests that many Swap Dealers will end-up in Add-On territory for OTC swaps clearing at CCPs This means that swaps become incrementally ever more expensive to trade relative to futures From a liquidity point of view, […]