BRL Interest Rate Swaps
The CME are due to begin clearing Brazilian Real interest rate swaps by the end of August 2015. I thought it worthwhile to uncover what we can see in the data prior to their launch. What is a BRL Swap? BRL swaps have a few peculiarities. Let’s have a brief look at the characteristics: Fixed […]
Boole Conferences Cork, Ireland, 2015
In 2015, University College Cork (UCC) celebrates the bicentenary of George Boole, 1815-64. Boole was appointed the first Professor of Mathematics at the University in 1849. To mark the bicentenary a series of international mathematical conferences, collectively referred to as the Boole Conferences 2015, are being held in Cork. Theme 7: Mathematical Modelling in Post-Crisis […]
USD OIS Swap Volumes

One of our more popular posts is Gary’s Feb 2014 article on Fed Fund Swap Nuances, so I thought it would be interesting to look into What the Data Shows for these products. First the highlights: USD OIS is the third-largest IR product $1 trillion gross notional was traded in July 2015 in the US […]
A Macro Look At OTC Clearing Data
We spend a lot of time analyzing IRS clearing activity for CME and LCH, primarily because it is close to home and about as much of a fist fight as we are going to see in swaps. But what about the rest of the world? There are 14 clearing houses that we monitor for OTC […]
July 2015 Review – Spreadovers, Butterflys and LCH SwapClear

Continuing with our monthly review series, let’s take a look at Interest Rate Swap volumes in July 2015. First the highlights: On SEF USD IRS July 2015 volumes were lower than June, but higher than April and May SpreadOvers had their best month since January Butterfly volume is up in both June and July USD Swap Curve […]
What is the deal with Agency Execution of Swaps
I’ve been wondering about the success of agency execution firms such as UBS Neo. The headline sales pitch for such a service seems to be: One technical integration/onboarding exercise to just one “SEF”, gaining a firm access to the liquidity of all 20+ SEF’s combined. A firm does not need to sign up and review/stay in […]
Quantitative Finance ‘GoodReads’
Two reading lists of books relevant to quantitative finance are provided using the GoodReads platform. Often I am asked to recommend good books to help a student, colleague or customer get a better grasp of quantitative finance. Instead of ad-hoc and incomplete lists, I thought it might be useful (especially for me) to have a […]
ECB QE and Eonia Swaps
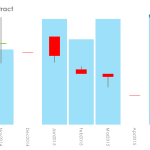
We take a look at Eonia invoice swaps, which match the dates for German bond futures traded at Eurex: From volume data, we see an increase in Eonia swap activity post-QE. The price action in Schatz appears closely related to short-end Eonia swaps, whilst in Bobls and Bunds it is harder to pin-down. The appearance of trades with […]
CFTC’s Roundtable on the Made Available to Trade Process – July 15, 2015
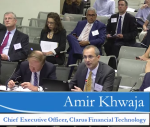
Amir presented ‘Data-based assessment of MAT’ at the CFTC’s division of market oversight roundtable on MAT meeting last week. The meeting has been recorded and is available on youtube (section starts at 0.53.04), (watch out for Tod in the audience at the top-left of the shot). The presentation slides are available for download here, […]
Webinar on CME-LCH Basis
The Recording of the Webinar is available here Please join us, CME and ICAP on Thursday 23rd July at 11:30am EST, by registering here.