Single name CDS activity surges across Big Tech and European Financials
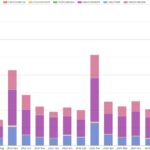
This blog looks at the most active issuer names traded in September 2026 on US-reported single-name credit default swaps (CDS). This follows the March 2026 edition in the series – aligned to the conventional CDS volume peaks near March and September IMM dates. Key takeaways Data coverage I use the “Most Active” tab from SBSDRView to […]
Q3 rates swaps volumes: new USD high, other majors off highs
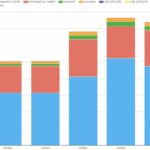
This blog covers Q3 2026 volumes of global cleared rates swaps risk-trading products focusing on OIS, fixed-float IRS, and zero-coupon swaps – including each product for a currency if it had a material volume share. We exclude FRAs (primarily used for reset exposure hedging) and basis swaps (primarily used for interest rate basis hedging). Key takeaways In Q3 […]
Q3 cross-currency volumes were 26% below Q1 while BGC, ICAP, and Tullett Prebon gained market share
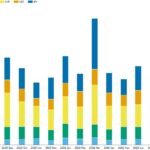
This blog reviews Q3 2026 US-reported volumes and D2D platform market shares of major currency cross-currency swaps risk-trading, continuing the quarterly series from the Q2 edition. Key takeaways In Q3 2026 major currency cross-currency basis swaps: Read on for supporting analysis of charts and data created in SDRView. Blog scope We continue to focus on US-reported […]
Q3 D2D platform rates swaps: Tullett Prebon and electronic platforms gain share
This blog reviews the Q3 2026 D2D platform market share dynamics of major currency rates swaps risk-trading, continuing from the last quarterly edition. Key takeaways We sourced the charts and statistics from SDRView. Background Here we focus on D2D platforms’ bread-and-butter trading activity in cleared OIS and fixed float IRS. We exclude compressions to keep the focus on risk-trading. […]