Single name CDS activity surges across Big Tech and European Financials
This blog looks at the most active issuer names traded in September 2026 on US-reported single-name credit default swaps (CDS). This follows the March 2026 edition in the series – aligned to the conventional CDS volume peaks near March and September IMM dates. Key takeaways Data coverage I use the “Most Active” tab from SBSDRView to […]
Q3 rates swaps volumes: new USD high, other majors off highs
This blog covers Q3 2026 volumes of global cleared rates swaps risk-trading products focusing on OIS, fixed-float IRS, and zero-coupon swaps – including each product for a currency if it had a material volume share. We exclude FRAs (primarily used for reset exposure hedging) and basis swaps (primarily used for interest rate basis hedging). Key takeaways In Q3 […]
Record Q2 2026 CCP IM for ETD
From the end of June 2026 quarterly CPMI-IOSCO Quantitative Disclosures by clearinghouses captured by CCPView, this blog focuses on cleared IM for rates swaps, credit derivatives (CRD), and exchange-traded derivatives (ETD). Key takeaways The Q2 2026 disclosures show different IM dynamics across the three product groups: IM for cleared rates swaps Chart 1: IRS IM by […]
Derivatives innovation: H1 2026 Eris swap futures exceed 10% of MAC SOFR swaps
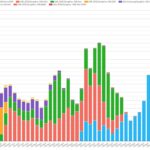
This blog shows new volume and OI peaks and tells the story of how they reached them. Key takeaways How did swap futures develop? Swap futures were created soon after the 2008 global financial crisis. This was a period of both re-regulation and experimentation driven by G20 regulators’ consensus to standardize OTC derivatives and move […]
Rates derivatives CCP shares show mixed Q2 dynamics
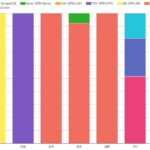
This is the Q2 2026 edition of our quarterly blog on competition between rates derivatives exchanges and CCPs. It can be directly compared with the Q1 edition and is a complement to our recent Q2 blog on cleared rates swaps volumes. Key takeaways In Q2 2026, the quarter on quarter (QoQ) shifts in the CCP […]
Marginal record Q2 volumes for cleared FXD and US-reported NDFs
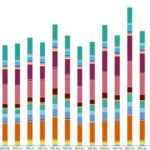
This blog looks at Q2 2026 volumes of FX derivatives (FXD), following the record volumes noted in Q1. Key takeaways In Q2 2026: Read on for more analysis, explanation and volume charts and statistics from CCPView and SDRView. Note on volume statistics Cleared FX OTC derivatives covered by CCPView include NDFs, FX options, FX forwards, NDOs, and spot […]
Q2 2026 cleared rates swaps: 17% below the Q1 high but up 23% YoY
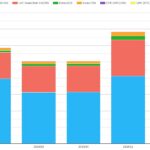
This blog covers global notional volumes of cleared rates swaps in quarter two (Q2) 2026, focusing on volumes of OIS, fixed-float IRS and zero-coupon swaps with a material volumes’ share for each currency. Key takeaways In Q2 2026 global core cleared rates swaps volumes were US$262 trillion notional – up 23% YoY but down 17% from their Q1 2026 […]
Record Q1 2026 CCP IM disclosures
At the end of March, clearing houses published their Q1 2026 CPMI-IOSCO Quantitative Disclosures. This blog focuses on cleared IM for rates swaps, credit derivatives (CRD) and exchange-traded derivatives (ETD) together with a sample of the other disclosures. Key takeaways 31 March 2026 saw a new record in CCP-disclosed cleared IM for each of the three […]
US firms powered March 2026 iTraxx swaps volume growth
This blog covers credit derivatives (CRD) trading volumes in March 2026, both at CCPs and as reported in the US. We sourced the charts and statistics from CCPView, SDRView and SBSDRView. Key takeaways Notes on CRD volumes We focus on the months of March and September because the standardized CRD maturity dates on the two months’ […]
Q1 2026 exchange/CCP shares of cleared rates derivatives
This blog is the first edition of what will become a regular quarterly blog on competition between rates derivatives exchanges and CCPs measured by market share of trade notional cleared. Key takeaways In Q1 2026, the exchanges and CCPs market shares of the more competitive cleared derivatives products were as follows. Read on for more […]