Liquidity
Clarus tools help our users monitor liquidity risk across Swaps markets. In this blog, we quantify how much risk has traded this year across a broad range of swap subtypes, and across venues. We show how our clients can use SDRView to stay on top of the risks they are running. Liquidity Concerns According to […]
Pricing and Arbitraging the CME/LCH Basis
I’ve been pondering the appropriate spread between LCH and CME. It would seem to me that every firm should have their own true cost of putting on a swap at CME or LCH, based upon a multitude of factors not limited to how they are currently positioned. I thought it worthy to explore what these […]
Technical Analysis in Swaps
Following on from last week’s look at the volatility in EUR swaps markets, I wanted to switch my attention to see the knock-on effect in USD swap markets. So let’s look at some of the Technical Analysis that is possible via our suite of SDRView tools. Is That an Outright or a Spread Sir? One […]
LCH Makes Gains vs CME in USD IRS (8-12 Jun 2015)
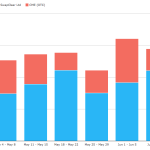
Following my blog on CME and LCH: What Happened on May 19 and Jun 12, I wanted to re-visit the data now that we have another week of published volumes. Weekly Volumes Using CCPView lets look at weekly volumes of gross notional for just USD IRS for the past 6 weeks and compare CME IRS Volumes with LCH […]
A New Flavor of Invoice Spreads?
If you’ve been following the package trade exemption, you’d know that Invoice spreads are one of the last package trades yet to be traded on-SEF. The swaps are due to be SEF-required (MAT’d) in November of this year. I wrote a blog last year about the issue here. While I am no further educated on just […]
CME and LCH: What Happened on May 19 and Jun 2?
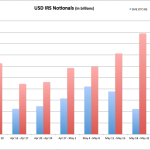
Continuing with the theme of CME-LCH Basis which has been a phenomenally popular blog, I wanted to look at whether there has been an impact on volumes of Cleared USD Interest Rate Swaps at CME and LCH. Weekly Volumes Using CCPView we can extract weekly volumes of gross notional for just USD IRS for the […]
Volatility and Volumes in Europe
Since European Rates made all-time lows on 17th April, we have seen an unprecedented sell-off in European fixed income. SDRFix shows the moves from 17th April to the close on 5th June 2015: Showing: A huge steepening on the yield curve, with 30y rates 90bp higher (!), versus 2y higher by only 7.2bp. 5y are […]
The Issue with Anonymous Order Books in Swaps
The conversation seems to be heating up again about the topic of anonymous order books for the OTC swap market. The topic has been out there for well over a year, however really had not been in the press or acknowledged by the CFTC until SEFCON V in November 2014. It remains un-addressed. The CFTC […]
Swap Equivalents via Waves
In a recent paper, “Calculating Delta Risks and Hedges via Waves (2015)“, Hagan deals with an old practical problem–determining risk and hedges on an interest rate book. In older systems a delta hedge report is often implemented by perturbing quotes used to construct the yield curves, restripping the curves and then revaluing the book. As […]
May 2015 Review – CCP Basis and Increased Client Flows
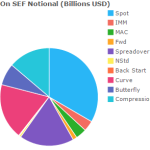
A lack of market volatility didn’t prevent healthy volumes this month. CCP Basis trading emerged in the D2D market. In USD IRS, extensive activity in Butterflies led to a rebound in volumes from the April lows. Most of this increase was seen on Dealer to Client SEFs, helping them to a 55% market share year-to-date. USD On-SEF […]