The IMM Roll for Swaps – What is it and what are the volumes?
Every quarter, monthly SEF volumes are distorted artificially higher by IMM roll activity. What is it and how can we identify the trades? The History of the IMM Roll The International Monetary Market (IMM) was a division of the CME back in the 1970s. There is a great essay here for the history buffs. In […]
Client Portfolios will Dominate CCP Risk

Using Client Open Interest figures we can project the share of CCP portfolio risk due to Clients once Clearing reaches a mature state. This will take several years as legacy non-cleared Rates portfolios (which dominate global notional outstanding) need to run off and be replaced by cleared trades under the US, EU and Asia client clearing mandates. However, […]
Trade Surveillance in Swaps Trading
Swap Execution Facilities (SEFs) and Swap Data Repositories (SDRs) mean that it is now possible to implement effective Trade Surveillance in the OTC Swaps market and to do so in an analogous manner to the Futures market. Swap Dealers or Major Swap Participants can and should compare their executed trades with the trades reported in […]
Swap Curve and Fly Trading: What goes in, must come out
Curve and Fly trading looks like a simple old game – existing trades are ripped-up and replaced with spot-starting hedges. So why don’t people do that across the Bloomberg SEF? Curve and Fly Trades Today, we indulge in a little bit of data mining for our recently launched Curve and Fly feature. This is a fascinating […]
Swap Curve and Fly Trades: A quarter of all trades are not what they first seem
We now identify package trades within SDR data in real-time. These packages represent 25% of reported trades. Users can access this analysis via our SDRView Pro application, further increasing the utility and transparency of the data within OTC markets. This is a good example of how we can add simplicity and clarity to the data […]
HFT in the Swaps market – it’s a good thing!
I thought it was very interesting this week that Commissioner Giancarlo mentioned the potential emergence of HFT in the swaps trading landscape. From a quick read of his remarks, it sounds like he is not a great supporter of continuous CLOB trading as the only mode of swap execution. But what if enabling HFT in […]
Year End Turn Rates
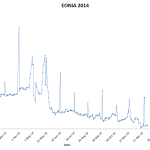
The year-end turn-rate (or the turn-of-the-year rate) is the interest rate for the period between the last business day of the year until the first good business day in the next year. For example, in the US the 2014 turn rate is the interest rate for the period between 31-Dec-2014 until 2-Jan-2015. The rate can […]
Swaps Compression Continued
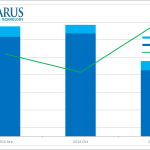
Last week we introduced the idea that we can identify compression trades within the SDR data. Combining this with information direct from SEFView, we now have good estimates for compression volumes being traded across the three SEFs currently active in this market – TrueEx, BSEF and Tradeweb. Due to the nature of the exercise, we […]
IR Swap Prices on Reuters, Bloomberg and SDR
SDRView Pro shows the latest IR Swap trade prices reported to US Swap Data Repositories with a 15-minute snap of prices from ICAP. However this requires a user to use a Web browser and login to the SDRView application. We have all heard how difficult it is to get screen real-estate on a traders desktop; even with […]
USD Swaps Liquidity
SDRView now includes DV01 data for USD Swaps. This can be seen in SDRView Researcher, and also in SDRView Pro via both the Web application and the API. I have been using the API to access the data through Excel, and over the course of the past week I’ve been exploring the concept of a liquidity […]