JAVELIN’S 2-DAY VAR LETTER: WHAT DOES IT MEAN?
A short while ago I saw the letter written by Javelin to the CFTC regarding MAC swaps and margin. The press release can be found here. My brief synopsis: Swap futures are equivalent (in terms of risk) to cleared OTC MAC contracts Swap futures enjoy 2-day VaR margining (SPAN or SPAN like) OTC MAC contracts are […]
Price Making in Swaps and Sharpening your Axe
Market making in Swaps is a business in the midst of significant change. Regulatory drivers are increasing cost and complexity and while central clearing has helped, it has not yet simplified the business to one which is automated, high-volume and low cost. When making prices Swap dealers have “usually had an axe”, meaning a bias to […]
Stress Testing of Initial Margin and Procyclicality post Oct 15th
There has been much comment on the market moves in the US Treasury market on October 15, 2014. Our article Swaps and the Flash Crash described what we saw in Interest Rate Swaps. So I thought it would be interesting to look at what this period of market stress and higher volatility means for Cleared Swap Margin requirements. And […]
Why a Margin Forecast is important
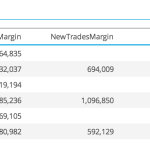
Variation Margin and Initial Margin are required for a Cleared Swaps Portfolio. Each day a Clearing House will calculate margin requirements in an overnight batch and margin statements will be sent to Clearing brokers and then on to Clients. Just as a trader or a portfolio manager should not leave for the day without knowing their […]
Mechanics and Definitions of Spread and Butterfly Swap Packages
(a.k.a. Spreads and Butterflies Part Zero) Interest Rate Swap markets are jargon-heavy. Traders live and breathe the language. Professional investors pick-up the nuances over time and the vicious circle of incomprehensibility is complete. However, now that Swaps markets have transitioned to electronic trading, will we see market-standard terms adopted across asset-classes? As a result, will […]
Forward IRSwaps and Initial Margin
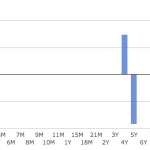
In this article I will look at a Forward Start Interest Rate Swaps and the Initial Margin requirement for such a trade. We know from SDR data that Forwards Swaps are a very common trade type and if you are a regular reader of our blog, you will know that they represent the majority of Swap […]
CME IRS Margin Model Change
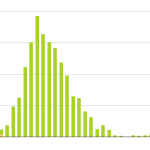
CME recently made a change to its margin model for interest rate swaps, see CME Advisory. This explains that on Aug 25, 2014, the model changed to use shifted log returns from log returns. The link in the advisory further states that “data for each currency will be shifted by 4% before computing log returns …..and […]
Swaps Compression: Clearing Fees and Margin
In my recent article, Swaps Compression and Compaction on trueEx and Tradeweb SEFs, I looked at the mechanics of these trades, the evidence in SEF and SDR figures and stated that the benefit was to reduce line items and clearing fees. In this article, I am going to take a deeper look at just the […]
Swaps Compression and Compaction on trueEX and Tradeweb SEFs

We are seeing increasing volumes of Cleared Swap Compression trades and this article will take a detailed looked at the mechanics of such trades. The Reason for Compression Lets start with the rational for compression trades. Every Cleared Swap trade shows up as a line item on a Clearing Statement and over time we have […]
The Principals of Swap Trading
Guest Blog Series Profile: Interest Rate Swaps trader. 12+ years’ experience, European and cross markets focused Yes, that is principals not principles. We are not talking stop-losses or take-profit levels today, although you might be able to leverage a relative value strategy out of the findings. With the first two blogs focussing on specific market […]